Refurbishing a restaurant can be funded through business savings, a commercial loan, asset finance, a merchant cash advance, grants or a combination of these options. The right choice depends on the refurbishment cost, your cash flow, how quickly you need the money and whether the work will interrupt trading.
Before applying for small business finance in the UK, prepare a detailed refurbishment budget and keep a separate cash reserve for unexpected costs. Compare the total amount repayable, fees, repayment structure and any personal guarantee—not just the advertised rate.
Key takeaways
| Question | Practical answer |
|---|---|
| What finance can fund a refurbishment? | Business loans, asset finance, merchant cash advances, grants, savings or a blended approach |
| Which option suits seasonal card sales? | A merchant cash advance may help because repayments usually move with eligible card sales |
| Should you use all your cash reserves? | Usually not. Keep working capital available for wages, stock, bills and unexpected costs |
| Can equipment be financed separately? | Yes. Asset finance may be suitable for eligible kitchen, payment or operational equipment |
| What should you compare? | Total repayment, fees, term, repayment frequency, security and early-settlement conditions |
| What improves an application? | Clear budgets, recent accounts, bank statements, sales records and a realistic repayment plan |
How much does a restaurant refurbishment cost?
There isn’t one standard restaurant refurbishment cost. Repainting a dining room and replacing furniture is very different from installing a commercial kitchen, moving plumbing or changing the building layout.
Your budget may include:
- Building and decorating work
- Kitchen equipment
- Electrical and plumbing upgrades
- Extraction and ventilation
- Flooring, lighting and furniture
- Toilets and accessibility improvements
- Signage and menus
- Professional fees
- EPOS and card payment equipment
- Temporary closure costs
- Initial stock for reopening
- Marketing for the relaunch
- A contingency allowance
The final figure will depend on the size and condition of the premises, the type of restaurant and the amount of structural work required. Local labour costs and your choice of materials will also affect the price.
Get written quotations wherever possible. If different contractors are responsible for the kitchen, electrical work and front-of-house design, place every quotation into one budget rather than treating each job separately.
Build the complete budget before seeking finance
A refurbishment budget shouldn’t stop at the contractor’s quote. You need to understand how much cash your business will require from the start of the project until normal trading resumes.
Include the cost of reduced trading
Will you need to close for a week? Can part of the restaurant remain open? Will deliveries continue while the dining area is unavailable?
A £30,000 refurbishment could create a larger funding requirement if you also lose two weeks of sales. Wages, rent, insurance and other bills may continue even when customer revenue falls.
For example, a Birmingham restaurant may decide to close its dining room while continuing takeaway and delivery orders. That reduces lost revenue, but the owner still needs to budget for lower sales and possible disruption.
Add a sensible contingency
Older restaurant premises can hide expensive problems. A contractor may discover damaged wiring, inadequate drainage or ventilation work that wasn’t visible during the first inspection.
Your contingency should reflect the uncertainty of the project. Discuss the appropriate amount with your contractor, accountant or project manager rather than choosing an arbitrary percentage.
Separate essential work from optional upgrades
Divide your plan into three groups:
- Work required for safety, compliance or continued operation
- Improvements expected to increase capacity or efficiency
- Cosmetic upgrades that could be postponed
This makes it easier to reduce the project if finance is limited. It also helps a lender understand why the investment is commercially sensible.
Ways to fund a restaurant refurbishment
Several types of small business finance in the UK may be available. Each has a different cost, repayment method and eligibility process.
1. Use retained profits or business savings
Using your own funds avoids borrowing costs and keeps the project simple. It may be suitable for a small cosmetic refresh or a refurbishment that has been planned and saved for over time.
However, don’t empty your business account simply to avoid finance. Restaurants still need working capital for ingredients, wages, utilities, rent and VAT bills.
If the refurbishment would use most of your available cash, combining savings with external finance may be safer than paying for everything yourself.
2. Apply for a business loan
A business loan normally provides a lump sum that is repaid over an agreed term. Depending on the facility, repayments may be fixed and made weekly or monthly.
Loans can be suitable for planned projects with a clear cost and timetable. A fixed repayment can make budgeting easier, but you’ll need to be confident that the restaurant can afford it during quieter months.
Before accepting an offer, check:
- The total amount repayable
- Interest and arrangement fees
- Whether the rate is fixed or variable
- The repayment term
- Early-settlement charges
- Security requirements
- Whether a personal guarantee is requested
A government-backed guarantee does not necessarily remove the borrower’s liability. Under the British Business Bank’s Growth Guarantee Scheme, for example, the borrower remains responsible for repaying the full facility even though the lender receives a government-backed guarantee.
You can learn more in the Switch & Save guide to small business loans in the UK.
3. Consider a merchant cash advance
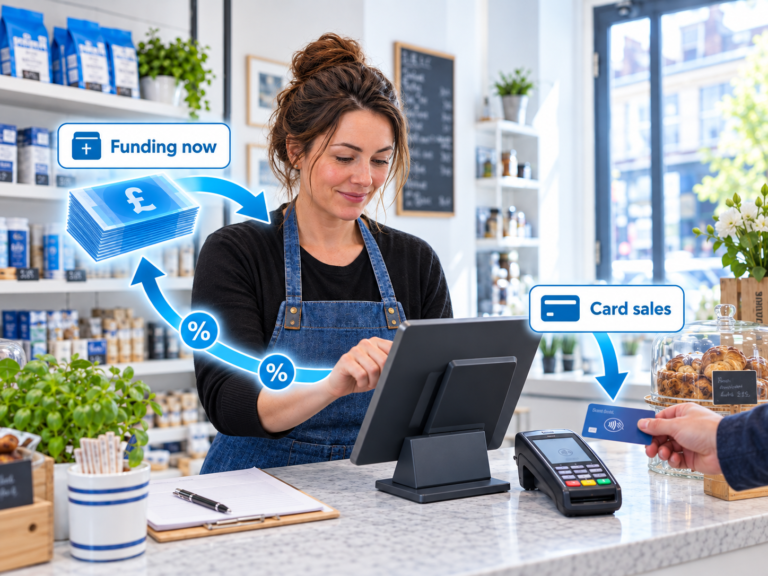
A merchant cash advance provides an agreed amount of funding in return for a portion of future eligible card sales. Instead of making the same fixed repayment each month, repayments usually rise and fall with card turnover.
Here’s how it works in practice. If your restaurant has a busy Saturday, more is collected towards the advance. If card sales are lower on a quiet weekday, the amount collected is normally lower too.
This structure may suit established restaurants, cafés and takeaways that process regular card payments. It can be useful where flexible repayments are more important than a conventional loan schedule.
However, flexibility doesn’t automatically make it the cheapest choice. Ask for the total repayment amount, collection percentage and any conditions before proceeding.
Read how UK businesses can access funding using card sales or compare a merchant cash advance with a traditional business loan.
4. Use asset finance for equipment
Asset finance can help spread the cost of eligible business equipment. Depending on the agreement, this might cover commercial ovens, refrigeration, dishwashers, furniture or other assets.
It can be helpful when equipment makes up a large part of the refurbishment budget. Rather than funding the entire project with one facility, you could finance eligible equipment separately and use another source for building work.
Ownership, maintenance responsibilities and end-of-term options vary between agreements. Check exactly what happens at the end of the term and whether the overall cost is reasonable.
5. Use a business overdraft or revolving credit facility
An overdraft or revolving facility can provide short-term access to working capital. It may help with timing gaps, contractor deposits or an unexpected invoice.
This type of finance is generally better suited to temporary needs than a large refurbishment that will take years to repay. Limits, interest rates and availability may also change, so don’t assume the facility will always remain available.
6. Look for grants and local support
Some businesses may qualify for grants related to energy efficiency, accessibility, regeneration, training or local economic development. Availability depends on your location, the project and the eligibility rules.
Grants are competitive and often fund only specific costs. You may also need to contribute part of the project yourself and receive approval before starting any work.
Search official local authority, business support and government funding sources. Business.gov.uk provides an overview of funding routes, including self-funding, grants, loans and equity finance.
Never delay essential work on the assumption that a grant will be approved.
7. Combine different funding sources
A blended approach can be practical when the project contains several types of spending.
For example, a restaurant might:
- Use savings for decoration and signage
- Use asset finance for new kitchen equipment
- Arrange business finance for structural work
- Keep an existing overdraft available for short-term working capital
This avoids placing every cost into one facility. It may also preserve cash for reopening, but you must consider the combined repayment burden.
How to choose the right funding option
Start with the purpose of the refurbishment. Are you replacing worn equipment, adding more covers, improving the customer experience or preparing to offer delivery?
Next, compare the finance with the way your restaurant earns money.
A fixed-term loan may suit predictable monthly cash flow. A card-sales-based option may be worth considering if turnover changes significantly between busy and quiet periods. Asset finance may make more sense for durable equipment than for decorating costs.
Compare each offer using the same information:
| Factor | What to check |
|---|---|
| Amount received | Is it enough to complete the planned work? |
| Total repayment | What will the finance cost from start to finish? |
| Repayment pattern | Fixed, variable, daily, weekly or monthly? |
| Term | How long will your business be making payments? |
| Security | Are assets or personal guarantees involved? |
| Flexibility | Can you repay early, and is there a charge? |
| Cash-flow impact | Can the restaurant manage payments during quiet periods? |
| Conditions | Are there restrictions on how the funds can be used? |
The cheapest-looking option isn’t always the most suitable. A repayment structure that places too much pressure on the business can become expensive in other ways, even if the advertised rate appears attractive.
How to prepare a strong finance application
Lenders and finance providers want to understand whether your restaurant can support the proposed funding.
You may be asked for:
- Recent business bank statements
- Filed accounts or management accounts
- Card-sales records
- Existing finance commitments
- Proof of identity and business ownership
- Contractor quotations
- A refurbishment budget
- Cash-flow forecasts
- An explanation of how the work will benefit the business
Keep your forecast realistic. If the refurbishment adds 20 seats, don’t assume every seat will be occupied throughout every service. Show conservative, expected and stronger trading scenarios if possible.
Accurate EPOS reporting can make this process easier. Sales by day, time, product and payment type can help demonstrate how the restaurant currently performs. Switch & Save provides AI-powered EPOS systems and card payment solutions that help businesses maintain clearer sales records.
How to refurbish without damaging cash flow
Plan the work around your trading pattern where possible. A seaside restaurant may avoid its peak summer period, while a city-centre lunch venue may schedule the most disruptive work over weekends or bank holidays.
You could also complete the project in phases. Start with essential kitchen and safety work, then refurbish the dining area and exterior later. Phasing can reduce the initial funding requirement, although it may increase disruption or contractor costs.
Agree payment stages with contractors before work begins. Avoid paying the full amount upfront without appropriate contractual protection. Keep invoices, warranties and completion records in one place.
Finally, monitor actual spending against the original budget. If one part of the project goes over budget, decide where savings can be made before approving more work.
Is financing a restaurant refurbishment worth it?
Finance may be worthwhile when the refurbishment has a clear business purpose and the expected benefit justifies the cost.
That benefit could include:
- Replacing unreliable equipment
- Increasing seating or kitchen capacity
- Reducing energy use
- Improving service speed
- Supporting takeaway or delivery sales
- Making the premises more accessible
- Creating a cleaner and more consistent customer experience
Not every improvement produces an immediate financial return. New décor may strengthen customer perception, but the effect is harder to forecast than adding a working oven or increasing the number of covers.
The decision should be based on realistic numbers, not simply the desire for a newer-looking restaurant.
Frequently asked questions
What is the best way to fund a restaurant refurbishment?
There’s no single best option. Business loans may suit planned projects with predictable repayments, merchant cash advances may suit restaurants with regular card turnover, and asset finance may be appropriate for equipment. The best choice is the one your business can comfortably repay.
Can I get restaurant finance with bad credit?
It may still be possible, but your options could be more limited or expensive. Providers may consider trading history, affordability, card sales and existing commitments as well as credit information. Compare the total cost carefully and avoid making applications you can’t afford.
Can I use a merchant cash advance for refurbishment?
Depending on the provider’s terms, a merchant cash advance may be used for refurbishment, equipment or other business costs. Eligibility is often linked to your trading and card-sales history. Confirm permitted uses before accepting an offer.
Can a new restaurant get refurbishment finance?
A new restaurant may find some forms of finance harder to obtain because it has little or no trading history. A detailed business plan, realistic forecast, personal investment or suitable security may help, but approval is never guaranteed.
Should I close the restaurant during refurbishment?
That depends on the work. Remaining open can protect revenue, but noise, dust and restricted access may affect safety and the customer experience. Discuss the work sequence with your contractor and never trade from an unsafe area.
Are restaurant refurbishment costs tax-deductible?
The tax treatment depends on the nature of the spending. Repairs may be treated differently from improvements, fixtures or equipment. Ask a qualified accountant to classify the costs correctly and explain whether capital allowances or other reliefs may apply.
How quickly can restaurant finance be arranged?
Timescales vary by provider, funding type and application complexity. Having recent accounts, bank statements, card-sales information and contractor quotations ready may reduce delays. Don’t commit to a contractor’s start date until funding is confirmed.
Take the next step
A successful refurbishment needs more than an attractive design. It needs a complete budget, realistic sales assumptions and a finance structure your restaurant can manage after reopening.
Switch & Save helps UK businesses reduce costs with AI-powered EPOS systems, card payment solutions and business finance.
Finance is subject to application, status, affordability and provider terms. This article is general information and isn’t financial, tax or legal advice.