If you need to buy stock before your busiest trading period, start by forecasting how much you can realistically sell, checking the cash already available and calculating the maximum repayment your business can comfortably manage. You can then compare supplier credit, a business overdraft, a working capital loan, inventory finance or a merchant cash advance.
The right choice depends on how quickly you need the money, when the stock is likely to sell and whether your income is steady or seasonal. The aim isn’t simply to secure as much funding as possible. It’s to buy the right stock without leaving your business short of cash for wages, rent, VAT and everyday costs.
Key takeaways
| Question | Short answer |
|---|---|
| What is seasonal stock finance? | Funding used to buy inventory before an expected rise in customer demand. |
| Which options should you consider? | Existing cash, supplier credit, overdrafts, loans, revolving credit, inventory finance and merchant cash advances. |
| How much should you borrow? | Enough to cover a well-supported stock requirement and related costs, with room for slower-than-expected sales. |
| What should you compare? | Total repayment, fees, repayment timing, security, personal guarantees and the effect on cash flow. |
| How can an EPOS system help? | It can show previous sales, product margins, stock movement and slow-selling items. |
| Is approval guaranteed? | No. Business finance is subject to eligibility, affordability checks, provider terms and approval. |
Why seasonal stock creates a cash-flow gap
Seasonal demand can be good for business, but preparing for it costs money.
A convenience shop may need extra drinks, snacks and ice creams before summer. A restaurant might order more ingredients and packaging ahead of Christmas bookings. A mobile phone shop may want additional devices and accessories before a major product launch.
The problem is timing. You normally have to pay for at least some of that stock before your customers buy it. Your money becomes tied up on shelves, in storerooms or with suppliers while you still have regular bills to pay.
This is a working capital issue. Working capital is the money your business uses for day-to-day operations. Seasonal businesses often experience predictable rises and falls in working capital because costs arrive before the related sales. (british-business-bank.co.uk)
Used carefully, small business finance in the UK can bridge that gap. But the finance should be based on realistic demand, not optimism alone.
Work out how much funding you actually need
Before applying for finance, calculate the size of the gap you need to cover.
A simple starting formula is:
Planned stock purchases + associated seasonal costs − available business cash − confirmed supplier credit = estimated funding requirement
Associated costs might include:
- Additional delivery charges
- Temporary staff
- Packaging
- Seasonal marketing
- Storage
- Insurance
- VAT where applicable
For example, imagine a Birmingham grocery shop plans to spend £18,000 on seasonal stock. It can safely use £6,000 of its own cash and has negotiated £4,000 of supplier credit.
Its estimated funding gap is:
£18,000 − £6,000 − £4,000 = £8,000
That doesn’t automatically mean the owner should borrow exactly £8,000. They should also test what happens if sales are lower than expected, stock arrives late or some products need to be discounted.
Use three sales forecasts
Create a conservative, expected and strong-sales forecast.
| Forecast | Expected result | Planning purpose |
|---|---|---|
| Conservative | Sales are below plan | Tests whether repayments remain affordable |
| Expected | Sales follow a realistic forecast | Forms the main purchasing plan |
| Strong | Demand is higher than expected | Helps plan reordering without overbuying initially |
Your finance decision should remain manageable under the conservative forecast. If repayments only work when every product sells quickly at full price, the plan carries too much risk.
Ways to finance stock before a busy season
There isn’t one best option for every business. The right method depends on your trading history, payment mix, supplier relationships and how long the stock will take to turn back into cash.
1. Use retained business cash
Using money already in the business is usually the simplest option because there are no borrowing costs.
However, don’t empty your account to fill your shelves. You’ll still need enough cash for payroll, rent, utilities, tax obligations and unexpected expenses.
Set a minimum cash reserve first. Only use the amount above that reserve for seasonal stock.
2. Negotiate supplier credit
Supplier credit allows you to receive goods now and pay after an agreed period, such as 30 or 60 days.
This can align payment more closely with the point at which your stock starts selling. It may also avoid the need for external borrowing.
Ask your supplier about:
- Longer payment terms
- Split payments
- Smaller initial orders with rapid replenishment
- Sale-or-return arrangements
- Discounts for planned bulk orders
- Credit limits during your peak season
Supplier credit can be valuable, but late payment may damage the relationship. Agree terms clearly and make sure the due date appears in your cash-flow forecast.
3. Business overdraft
An overdraft provides short-term flexibility through your business bank account. You generally pay interest on the amount used rather than the entire limit.
It may suit a relatively small and temporary seasonal gap. For example, a café could use an overdraft to cover extra supplies for a short run of Christmas events and repay it as revenue arrives.
Check the interest rate, arrangement fees, limit and whether the facility can be reduced or withdrawn. Don’t treat an overdraft as permanent working capital.
4. Working capital loan
A working capital loan can provide a lump sum for stock and other short-term operating costs. Depending on the product, repayments may be fixed over an agreed period.
This offers predictable payments, which can make budgeting easier. The drawback is that repayments usually continue even if seasonal sales arrive later than expected.
Working capital finance can be secured or unsecured. Secured finance uses business assets as security, while unsecured applications tend to place greater weight on turnover, trading history, creditworthiness and affordability. (british-business-bank.co.uk)
Compare the annual interest rate, all fees and the total amount repayable—not just the advertised monthly payment.
5. Revolving credit facility
Revolving credit allows your business to draw funds when required, repay them and potentially use the facility again.
It can suit businesses that purchase stock in several stages. Instead of borrowing the full amount at once, you may be able to draw money as supplier invoices become due.
This flexibility can be useful, but frequent withdrawals and short repayment intervals may become expensive. Review the full terms carefully. (british-business-bank.co.uk)
6. Purchase order or inventory finance
Purchase order finance may help when you have a confirmed customer order but lack the cash to pay the supplier needed to fulfil it. The finance provider generally funds the supplier payment, subject to its checks and terms. (british-business-bank.co.uk)
Inventory finance is specifically designed to support the purchase of stock. It’s more common in sectors where goods have a measurable resale value, such as vehicles, electronics or wholesale products.
These products can be useful, but they won’t suit every shop, restaurant or takeaway. Ask what stock is eligible, how it will be valued and what happens if it takes longer to sell.
7. Merchant cash advance
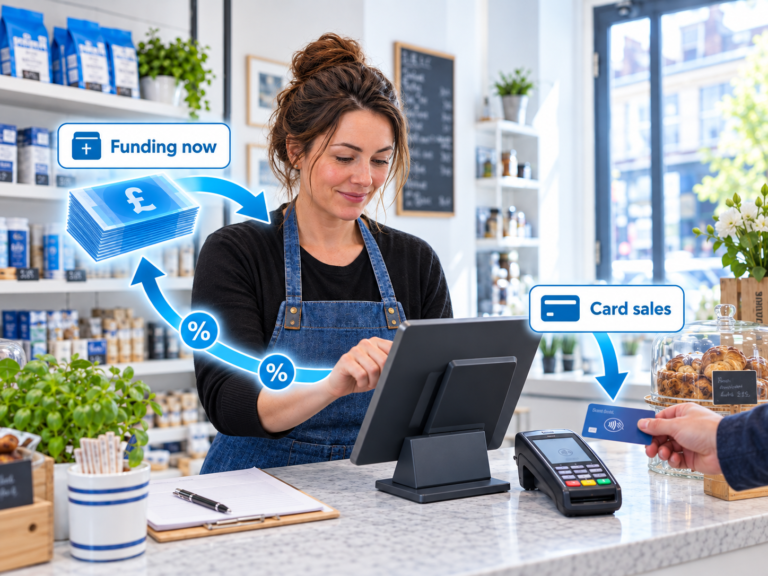
A merchant cash advance provides funding in exchange for an agreed share of future card sales. Repayments usually rise when card takings are stronger and fall when they are quieter.
This may suit retailers and hospitality businesses with regular card transactions and variable seasonal income. Merchant cash advances can be used for purposes including inventory and working capital, although their overall cost may be higher than some traditional lending options. (british-business-bank.co.uk)
Before accepting an offer, check:
- The amount you’ll receive
- The total repayment amount
- The percentage taken from card sales
- The likely repayment period
- How refunds and chargebacks are treated
- Whether other fees or restrictions apply
You can read more about how a merchant cash advance works or complete a business finance eligibility check.
Funding is subject to eligibility, affordability, provider checks, approval and terms.
How to compare your finance options
The cheapest-looking offer isn’t always the most suitable.
Compare each option using the same information:
| Factor | What to check |
|---|---|
| Total cost | Interest, fixed fees, arrangement charges and total repayment |
| Repayment pattern | Fixed monthly payments or repayments linked to sales |
| Speed | Whether funds will arrive before supplier deadlines |
| Term | Whether the repayment period matches the stock-selling cycle |
| Security | Assets, stock or personal guarantees required |
| Flexibility | Early repayment rules and access to further funds |
| Cash-flow effect | The amount left after finance deductions and regular costs |
| Risk | What happens if sales are delayed or below forecast |
Think in terms of pounds, not just percentages. Ask the provider to show what the finance is expected to cost in total.
It’s also sensible to check whether repaying early changes the cost. Some products charge interest over time, while others use a fixed fee that may not reduce in the same way.
Use EPOS data to plan stock more accurately
Good stock finance starts with good sales information.
An AI-powered EPOS system can help you review:
- Sales from the same period last year
- Your fastest-selling products
- Gross profit by product or category
- Stock currently on hand
- Slow-moving and unsold products
- Peak trading days and times
- Sales by location
- The effect of previous promotions
Suppose your EPOS report shows that premium gift boxes sold slowly last Christmas, while lower-priced bundles sold out twice. That evidence can help you adjust the next order rather than simply buying more of everything.
Your reports can also help you phase purchases. You might place a smaller opening order and agree quick replenishment with the supplier. That reduces the amount of cash tied up in stock and lowers the risk of end-of-season discounting.
Let’s say, a gift retailer expects higher December demand but wants stock delivered in October. It uses last year’s EPOS data to remove slow-moving lines from the order.
The owner funds part of the purchase with retained cash, negotiates 30-day supplier terms and uses a small revolving facility for the remaining gap. This spreads the funding rather than placing the entire purchase on expensive short-term finance.
Or a restaurant has confirmed group bookings and expects stronger card sales in November and December. It needs more ingredients, drinks, packaging and temporary staff before deposits and final payments arrive.
The owner compares a fixed loan with sales-linked finance. Because revenue varies each week, a merchant cash advance may offer a repayment pattern that follows card takings. The restaurant still checks the total repayment carefully before proceeding.
And a grocery shop wants extra cold drinks, barbecue products and ice creams. Instead of borrowing enough for one very large order, the owner checks weekly sales reports and arranges frequent replenishment.
This lowers the initial funding need and reduces the chance of being left with seasonal stock when the weather changes.
Mistakes to avoid
Buying stock without checking previous sales
A busy season doesn’t make every product a bestseller. Review sales by item, category and margin before ordering.
Borrowing based on your best-case forecast
Plan repayments around conservative sales. Strong trading should give you extra breathing room, not rescue an unaffordable agreement.
Forgetting costs beyond stock
Delivery, storage, staffing, marketing and packaging can all increase before the season begins. Include them in the cash-flow forecast.
Comparing only the headline rate
A low-looking rate may not reveal the total cost. Compare fees, repayment structure, security requirements and the total amount payable.
Ordering too much too early
Early ordering may secure supply, but it ties up cash for longer. Where possible, negotiate staggered deliveries or rapid reordering.
Using short-term finance for unsellable stock
Finance works best when the stock has a clear route to sale. Avoid borrowing heavily for products with uncertain demand, limited shelf life or poor margins.
When should you arrange seasonal stock finance?
Start planning at least several weeks before you need to pay suppliers. Businesses with complex orders, imported products or longer lender assessments may need to begin earlier.
A practical timeline is:
- Review previous seasonal sales.
- Check current stock and open purchase orders.
- Build conservative and expected forecasts.
- Ask suppliers about prices, deadlines and credit terms.
- Calculate the funding gap.
- Compare suitable finance options.
- Read the agreement and model repayments.
- Place orders with time for delays.
Applying at the last minute limits your options. It may also push you towards a more expensive product simply because it can release funds quickly.
How Switch & Save can help
Switch & Save supports UK retailers and hospitality businesses with AI-powered EPOS systems, card payment solutions and access to business finance through its finance partner.
Your EPOS data can help you understand what sold, which products generated the best margins and how much stock you’re carrying. If you take regular card payments, you may also be able to explore funding with repayments linked to future sales.
Switch & Save helps UK businesses reduce costs with AI-powered EPOS systems, card payment solutions and business finance.
Business finance is subject to eligibility, affordability checks, provider approval and terms. This article provides general information and isn’t financial advice.
Frequently asked questions
What is the best way to finance seasonal stock?
There’s no single best option. Supplier credit or existing cash may be suitable when the funding gap is small. An overdraft, working capital loan or revolving facility may suit a temporary cash-flow need. Businesses with regular card sales may also consider a merchant cash advance.
Compare the total cost, repayment timing and effect on cash flow before deciding.
Can I get business finance to buy stock in the UK?
Yes. Some UK finance products can be used for stock, inventory or general working capital. Availability depends on the lender, your business circumstances, affordability and the proposed use of funds.
How much should I borrow for seasonal stock?
Borrow only what your realistic forecast says you need. Account for available cash, supplier credit, existing inventory and other seasonal expenses. Test whether repayments remain affordable if sales are below expectations.
What information might a finance provider request?
Requirements vary, but providers may ask for bank statements, accounts, management information, sales records, card-turnover data and details of existing borrowing. They may also assess the business’s credit history and affordability.
Can a new business finance seasonal inventory?
It may be possible, but a limited trading history can reduce the available options. A new business might consider owner investment, supplier credit, a start-up finance product or a smaller phased stock order. Every provider uses its own eligibility rules.
Is a merchant cash advance a business loan?
No. A merchant cash advance is generally structured as an advance against future sales rather than a conventional loan with fixed monthly instalments. Make sure you understand the total repayment and the share of card sales that will be collected.
Can an EPOS system help with a finance application?
An EPOS system doesn’t guarantee approval, but accurate sales and stock reports may help you understand your funding requirement and provide clearer trading information where requested.
What happens if the busy season is quieter than expected?
You’ll still be responsible for the finance under the agreed terms. This is why you should use a conservative forecast, retain a cash buffer and avoid buying more stock than your business can reasonably sell.